Green Thumb Industries Inc. (CN:GTII) has become a proxy for a broader question in cannabis retail investing: does a favorable policy narrative actually change what a multi-state operator earns, or does it just change how investors feel about the stock? As of October 14, 2026, no company-specific announcement has been independently confirmed, and no verified intraday price or volume figure anchors this discussion. That absence of a hard catalyst is itself the point. The debate around GTII right now is a framework for evaluating the business, not a reaction to a confirmed event.
Why Sector Optimism Doesn't Always Translate to Cash
Cannabis retail sits in an unusual spot. It's a consumer category with rules that look nothing like typical consumer packaged goods. Section 280E still limits what operators can deduct federally, which means a dispensary chain can post healthy gross margin and still carry a disproportionate tax bill relative to actual profit. That mechanic alone explains why headline revenue growth at a multi-state operator can mean less than it appears to. The real test is whether same-store sales are holding up, whether wholesale pricing pressure is compressing margin at the cultivation and processing level, and whether operating cash flow is funding expansion without forcing dilutive equity raises or expensive debt. Federal policy chatter can lift sentiment across the sector in a single session. It does not retroactively fix a balance sheet.
What Operators and Investors Should Actually Track
For GTII specifically, the indicators that matter are the ones that show up in filings, not in press cycles:
- Same-store sales trends across its retail footprint, which reveal whether growth is organic or acquisition-driven
- Gross and operating margin movement, particularly as wholesale pricing continues to soften in several mature adult-use markets
- Free cash flow after capital expenditure, not just adjusted EBITDA, since capex on cultivation buildout or new store openings can quietly consume reported profitability
- Debt maturity schedule and refinancing terms, given how costly cannabis-specific lending remains relative to conventional retail credit
- Any federal policy movement - rescheduling discussion, banking access, 280E relief - and whether it's procedural or substantive
Here's the catch: a strong narrative around federal reform has circulated in cannabis investing for years without full resolution. Investors who price in an outcome before it's codified can find themselves exposed if timelines slip again. That's not pessimism; it's just the pattern this sector has shown repeatedly.
Reading the Balance Sheet Before the Headline
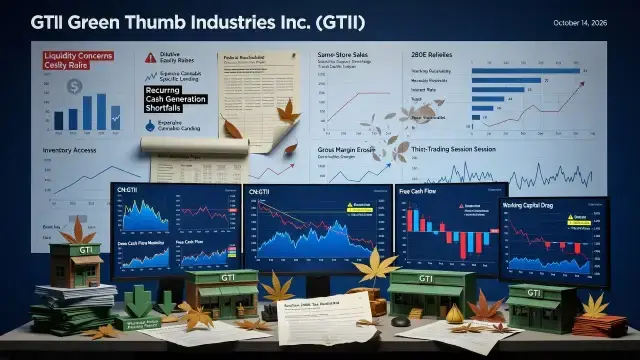
A rigorous look at CN:GTII starts with liquidity and financing flexibility, not store count. Does recurring cash generation cover essential capex, debt service, and any shareholder distributions without repeated external funding? A operator with a durable balance sheet can absorb a slow regulatory timeline. One that's stretched thin may be forced into asset sales or equity issuance on unfavorable terms exactly when the market is least forgiving. Receivables growth, inventory shrinkage, and working capital drag all matter more than they get credit for in sector-wide bullish commentary. None of this is unique to Green Thumb - it applies across the multi-state operator class - but GTII's scale makes the distinction between accounting earnings and operating cash flow especially worth isolating.
Technical Signals Need Confirmation, Not Assumption
Without a verified October 14 closing price or volume series, no breakout level, percentage move, or moving-average signal can be responsibly asserted here. What investors can do is compare the next exchange-confirmed session against recent support and resistance zones, and watch whether any move holds on sustained volume rather than a single thin-trading session. Thin liquidity and concentrated ownership can exaggerate price swings around even minor news, which makes one-day reactions a weak basis for conviction either way.
The near-term outlook for Green Thumb Industries remains conditional rather than directional. A constructive case requires demonstrable progress in same-store performance, margin stability, and clearer cash-flow visibility tied to actual federal policy movement - not just discussion of it. A cautious case emerges if execution slows, debt terms tighten, or the market prices in benefits that haven't yet materialized. The sound approach is scenario analysis against verifiable milestones, not a bet on sentiment.